The High Price of Protection: How Black and Hispanic Communities Are Bearing the Brunt of the U.S. Home Insurance Crisis

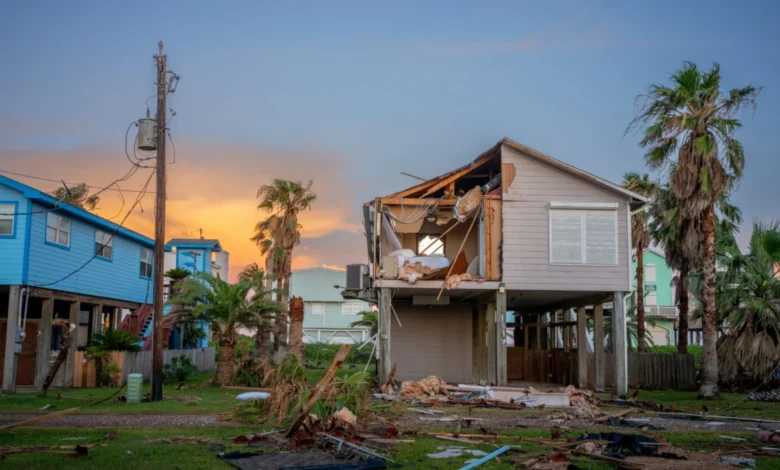
As the United States grapples with a compounding affordability and climate crisis, a hidden financial penalty is falling squarely on the shoulders of Black and Hispanic homeowners. Across the nation, families living in predominantly communities of color are paying disproportionately higher premiums for home insurance than their white counterparts, even when purchasing identical coverage for structurally similar properties. This systemic discrepancy is exacerbating the racial wealth gap, creating a formidable barrier to homeownership, and exposing vulnerable populations to severe financial distress as climate change accelerates the frequency and intensity of catastrophic weather events.
The scope of this disparity was brought to light by a comprehensive July report released by the Consumer Federation of America (CFA), a prominent nonprofit advocacy organization representing nearly 250 consumer protection groups. The findings paint a sobering picture of modern housing inequity, revealing that systemic financial burdens are deeply embedded within an industry facing unprecedented turbulence.
Unpacking the Disparities: The Numbers Behind the Crisis
According to the CFA report, the financial penalty levied on homeowners of color is substantial. Homeowners residing in predominantly Hispanic ZIP codes pay, on average, a staggering 30 percent higher premium for home insurance than those living in predominantly white communities. In monetary terms, this translates to an average of $950 more annually. For predominantly Black ZIP codes, the narrative is similarly grim: homeowners face an average 16 percent higher premium, costing them roughly $500 more per year than residents of white neighborhoods.
To arrive at these conclusions, researchers conducted a granular analysis comparing identical policy structures across different communities. This methodology successfully eliminated variables related to the differences among individual homeowners, the structural integrity or age of their homes, or the specific coverage limits chosen. While local risk factors—such as proximity to coastlines or flood zones—account for a fraction of the variation, the researchers discovered that a massive gap persisted even after controlling for these environmental variables.
Over the span of a standard 30-year mortgage, these compounding costs accumulate into life-altering sums. Families in predominantly Hispanic communities shell out at least an estimated $28,500 in additional insurance expenses over three decades, while those in predominantly Black communities face at least $15,000 in excess costs. In an era defined by a broader cost-of-living squeeze and severe housing inflation, these extra thousands of dollars represent a significant impediment to long-term wealth accumulation and financial security.
A Geographic Breakdown of Inequity
The national averages obscure sharp regional variations where the insurance penalty reaches alarming heights. The report highlights that the most acute disparities for Hispanic homeowners are concentrated in Florida—a state battered by relentless hurricanes and an ongoing property insurance meltdown. In Florida, residents of predominantly Hispanic ZIP codes pay an average of 58 percent more, or a remarkable $5,014 annually, for the exact same coverage as their counterparts in white communities. Other states with pronounced gaps for Hispanic populations include New York (20 percent, or $431), Washington (18 percent, or $278), Massachusetts (16 percent, or $244), and Kansas (15 percent, or $633).
For predominantly Black ZIP codes, the state-level disparities are led by Michigan, where residents face a 74 percent markup, translating to an extra $1,768 per year. Pennsylvania follows closely with a 57 percent gap ($1,048), while New Jersey (22 percent, or $332), Massachusetts (20 percent, or $321), and New York (19 percent, or $417) also exhibit severe pricing imbalances.
These localized spikes underscore how broader state-level insurance crises—driven by carrier pullbacks, skyrocketing reinsurance costs, and climate exposure—do not affect all demographics equally. Instead, the burden is systematically heavier in communities that have historically faced marginalization and underinvestment.
Historical Roots: The Legacy of Redlining
To understand how modern insurance pricing disproportionately impacts communities of color, experts emphasize the need to examine the dark history of American housing policy. The current landscape cannot be divorced from the mid-20th-century practice of "redlining," a systemic method by which federal agencies and private lenders drew red lines on maps around neighborhoods deemed "hazardous" for mortgage lending, predominantly based on the racial composition of the residents.
Under this discriminatory system, residents within redlined districts were systematically denied home loans, preventing them from building home equity and leading to chronic disinvestment in local infrastructure, commercial development, and housing stock. Although explicit redlining was legally dismantled with the passage of the landmark Fair Housing Act in 1968, its structural legacy has proven remarkably persistent.
Decades later, the fingerprints of redlining remain visible across multiple facets of American life. Studies consistently link the historical boundaries of redlined districts to contemporary disparities in public health, educational funding, rates of incarceration, access to fresh and nutritious food, and the distribution of municipal infrastructure. Furthermore, due to a lack of tree canopy, older housing stock, and dense urban development with minimal green space, these same historically marginalized neighborhoods frequently manifest as urban "heat islands," leaving residents acutely vulnerable to extreme heat waves driven by climate change.
In the realm of insurance, this historical vulnerability translates into a vicious cycle. Because past disinvestment left communities of color with older infrastructure, lower average property values, and dense urban settings, modern risk-assessment algorithms often penalize these neighborhoods, perpetuating economic exclusion under the guise of objective actuarial science.
Industry Defenses and the Role of Actuarial Science
In response to the report’s findings, insurance industry representatives strongly rejected any allegations of intentional racial discrimination, maintaining that pricing models are strictly tethered to mathematical risk rather than demographic makeup.
Mark Friedlander, a spokesperson for the Insurance Information Institute (III), emphasized that the insurance rating system is heavily regulated, actuarially sound, and legally constrained.
"Using race, or any proxy for race, to set insurance rates is illegal in every U.S. jurisdiction, and state insurance regulators review and approve the rating factors insurers use precisely to guard against that," Friedlander said in a formal statement. He added that many of the communities identified in equity reports are situated in areas with objectively higher catastrophe exposure, older building inventories, or significantly elevated costs associated with rebuilding and repairing structures after a loss.
Insurance executives and trade groups argue that carriers are facing an existential crisis of their own. Driven by escalating global temperatures, greenhouse gas emissions from fossil fuels, and shifting weather patterns, the frequency of billion-dollar weather and climate disasters has climbed dramatically. Between 2021 and 2024 alone, the cost of home insurance for the typical American homeowner jumped by 24 percent, according to data cited by the Consumer Federation of America.
Faced with massive payouts from wildfires, hurricanes, and severe convective storms, insurance companies have increasingly restricted coverage, raised deductibles, or completely withdrawn from high-risk markets like California, Florida, and Louisiana. Within these tightening markets, consumer advocates argue that communities of color bear the harshest brunt of the contraction.
The Modern Threat: Algorithms, Credit Scores, and Artificial Intelligence
While explicit racial profiling by insurance agents is largely a relic of the past—punctuated by high-profile legal battles in the 1990s that forced companies like Nationwide and American Family Mutual Insurance Company to pay millions in discrimination settlements—experts warn that modern underwriting technology has introduced sophisticated, covert avenues for bias.
In the decades following the Fair Housing Act, insurance companies shifted away from manual neighborhood profiling toward automated, data-driven underwriting models. Today, insurers increasingly rely on proprietary algorithms, big data, and artificial intelligence (AI) to determine premium rates and process claims. While these technologies promise greater efficiency and precision, consumer advocates warn they can inadvertently codify and amplify historical inequities.
A prime example is the heavy reliance on credit scores in setting insurance rates. Previous research conducted by the Consumer Federation of America revealed that homeowners with lower credit scores face an average penalty of $1,996 annually—a staggering 99 percent markup—for identical insurance coverage. Because systemic wealth gaps, discriminatory lending practices, and historical economic disenfranchisement mean that Black and Hispanic consumers, on average, possess lower credit scores than white consumers, the use of credit-based insurance scoring acts as a powerful proxy for race.
Sharon Cornelissen, director of housing at the CFA and a co-author of the recent study, clarified that insurers are likely not feeding overt racial parameters into their algorithms. However, she warned that systemic bias frequently infiltrates automated systems when developers fail to audit for disparate impacts.
"A lot of this bias can kind of creep in if they’re not paying attention to potential unequal impacts," Cornelissen noted. "A lot of this could be through AI models or other factors that have a disproportionate impact on Black and Hispanic communities."
Economic Implications and Policy Recommendations
The broader economic implications of these disparities are profound. Housing stability is the cornerstone of middle-class wealth generation in the United States. When home insurance—a mandatory requirement for any mortgaged property—becomes exorbitantly expensive, it threatens the viability of homeownership for working-class families and communities of color.
Moira Birss, a senior fellow at the Climate and Community Institute, described the financial burden unfolding in states like Florida as an "enormous amount of money."
"And so when we’re thinking about how we’re having an affordability crisis in this country… that’s unconscionable," Birss said. "Unless the insurance industry wants to give us more information about why this is happening, it’s pretty hard not to interpret this as pretty serious racial discrimination."
To address the escalating crisis, housing and consumer advocates are urging state and federal policymakers to take decisive action. Key recommendations include:
- Enforcing Fair Housing Laws: State insurance commissioners and attorneys general must rigorously audit rating plans to detect and eliminate disparate impacts that disadvantage protected classes.
- Increasing Transparency: Regulatory bodies should demand full transparency from insurance companies regarding the specific data inputs, algorithms, and AI models used to establish premium rates.
- Reforming Underwriting Metrics: States should restrict or ban the use of non-consumer-controlled metrics, such as credit scores and ZIP code-level rating systems, that disproportionately penalize low-income communities and communities of color.
- Investing in Community Resilience: Industry leaders and policymakers agree that mitigating climate risk is essential for long-term affordability. However, advocates stress that federal and state resilience funding—such as grants for hardening roofs, updating building codes, and improving community-level flood defenses—must be equitably distributed to historically underserved neighborhoods rather than favoring wealthy enclaves.
As the climate crisis continues to reshape the American landscape, the intersection of race, housing, and insurance has emerged as a critical battleground for economic justice. Without proactive regulatory intervention and a concerted industry commitment to equity, the escalating cost of protection threatens to price communities of color out of climate-vulnerable regions entirely, locking in a new era of climate apartheid where financial security is determined by postal code and demographic heritage.
Related posts: